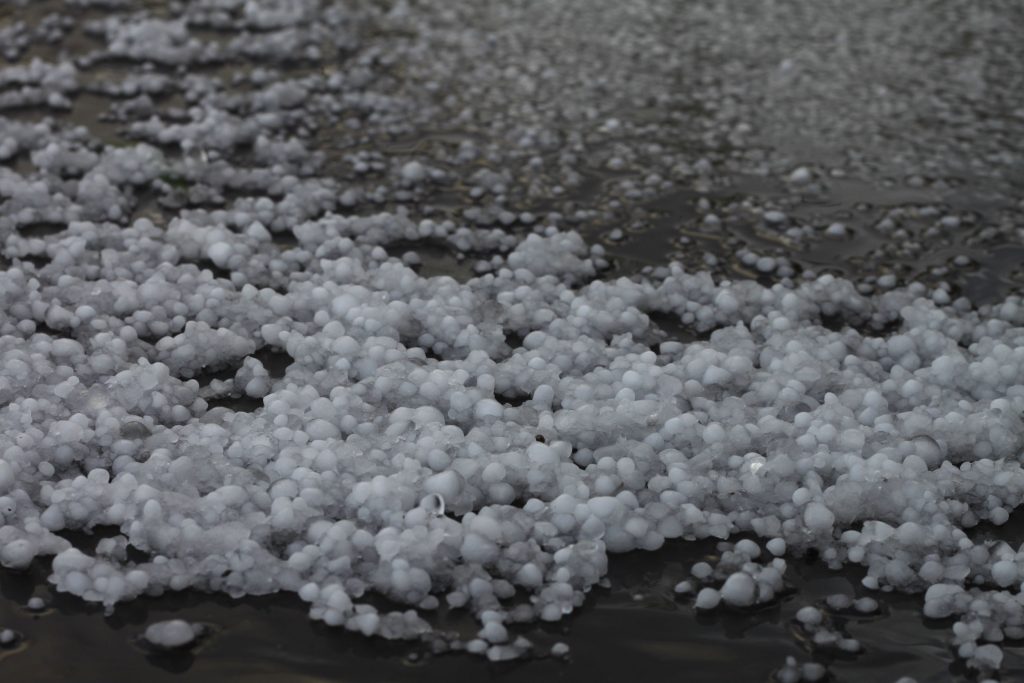
Manitoba recently lived through the largest hail event in the province’s history. On June 9, 2026, a storm tore through Winnipeg and generated more than 30,000 insurance claims, breaking a record that had stood since 1996. A second major hailstorm hit southwestern Manitoba weeks later, with hail the size of tennis balls and wind gusts near 80 km/h moving through the Brandon to US border corridor. By early July, the province had logged over 30,000 storm-related claims in a single month.
If your roof, siding, windows, or fence took a hit this summer, you’re far from alone, and you probably have questions. Here’s what actually happens next.
Does MPI cover storm damage to my house?
No. This is the single most common mix-up we see. Manitoba Public Insurance handles your vehicle, through Autopac, and that’s why you’ve heard about MPI opening hail response centres this summer. Your home, garage, fence, and detached structures are a completely different policy, sold through a private insurer and, in most cases, a broker. If a storm damaged your house, you’re filing that claim with your home insurance provider, not MPI. Two different systems, two different processes, and two different phone calls.
What does a standard home policy actually cover?
Most Manitoba home policies cover damage that’s sudden and accidental. Hail denting your siding, wind lifting shingles, a tree branch coming down on your roof, a window cracking from flying debris, all of that generally falls under wind and hail coverage. What it typically won’t cover is damage that built up gradually, like a roof that was already past its service life and finally gave out. That distinction matters, because it’s often the first thing an adjuster is trying to determine.
What should I do in the first 48 hours after a storm?
Document before you touch anything. Photos and video of the damage, from multiple angles, in daylight, before any tarping or temporary repairs. If you need to do emergency work to stop further damage, like tarping a roof or boarding a broken window, that’s expected and usually covered, but keep every receipt and take photos of the damage first. Then call your broker, not the roofing contractor who knocked on your door the day after the storm. More on that below.
How do wind and hail deductibles work?
Deductibles for wind and hail are often higher than your standard deductible, and some policies apply a separate percentage-based deductible specifically for these events. This is worth knowing before a storm hits, not after. If you’re not sure what your policy’s wind and hail deductible actually is, that’s a five-minute conversation with a broker that can save you a surprise during a stressful week.
Should I sign with the contractor who knocked on my door?
Be careful here. After every major Manitoba storm, out-of-province storm chasing crews show up fast, sometimes before homeowners have even called their insurer. Some are legitimate. Many pressure homeowners into signing contracts on the spot, inflate damage assessments, or disappear after collecting a deposit. Talk to your broker first. A good broker can tell you what your policy actually requires for documentation and repair, and can flag a reputable local contractor if you need one.
Will my rates go up because of a storm I didn’t even file a claim for?
Not directly. But large-scale catastrophic events do affect the broader insurance market over time. Canada recorded over $2.4 billion in insured severe weather losses in 2025, the tenth costliest year on record, and 2026 is already testing that. Insurers price risk based on regional exposure, which is part of why reviewing your coverage every year, not just after a bad storm, matters more in Manitoba than it used to.
What if my roof is fine now but I’m worried about next time?
This is the conversation worth having before storm season, not during it. A broker can walk through your actual coverage limits, your wind and hail deductible, whether your detached structures and fencing are properly covered, and whether your policy reflects any renovations or upgrades since you last reviewed it. Manitoba’s summer storm pattern isn’t going anywhere, and the best time to find a gap in your coverage is on a calm afternoon in May, not the morning after.
If you’re dealing with storm damage right now, or just want a second set of eyes on your coverage before the next one rolls through, we’re here for exactly that. That’s the job.