Farm & Rural Property Insurance
More property.
More to protect.
Coverage that understands rural life.
Rural properties come with a different set of challenges. Your home may share the property with barns, shops, garages, equipment, outbuildings and more. Whether you operate a farm, own an acreage or simply live outside the city, your insurance should reflect how you actually use your property.
Garriock helps Manitoba farm and rural property owners find coverage built around the property, the buildings and the risks that come with them.
Your Home
Protect the home you live in, whether it’s a farmhouse, acreage home or rural residence.
Outbuildings & Structures
Coverage can extend beyond your home to eligible garages, shops, barns, sheds and other structures on your property.
Equipment and Belongings
Protect eligible personal property, tools, equipment and other belongings kept on the property.
Liability
Rural properties can create unique liability risks. The right coverage can help protect you if someone is injured or your property causes damage to someone else.
Coverage varies by policy and condo corporation. Your Garriock broker can help explain where your coverage begins and what additional protection may be available.
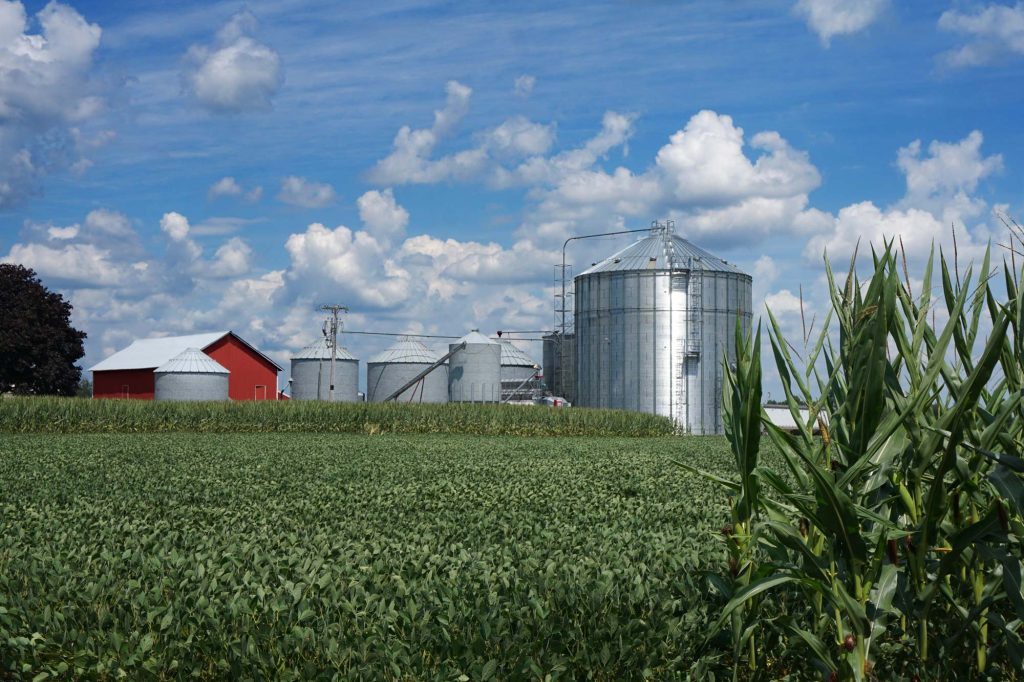
Rural Property Isn't Just a House
A rural property can have a lot more going on than four walls and a driveway.
You might have a detached shop full of equipment, a barn, grain storage, a private road, a well and septic system, or several acres of land to maintain. You may also have farming operations, livestock or other activities that change what your insurance needs to cover.
That’s why rural property insurance needs to look at the whole picture.
Your Property Has Its Own Set of Risks
No two rural properties are exactly alike.
A small acreage used primarily as a residence has different needs than an operating farm. A property with a large workshop has different exposures than one with a barn or livestock. Even things like how a building is heated, how often it’s occupied and what equipment is stored there can affect your coverage.
The goal isn’t to insure everything under the sun. It’s to make sure the things that matter are properly considered.
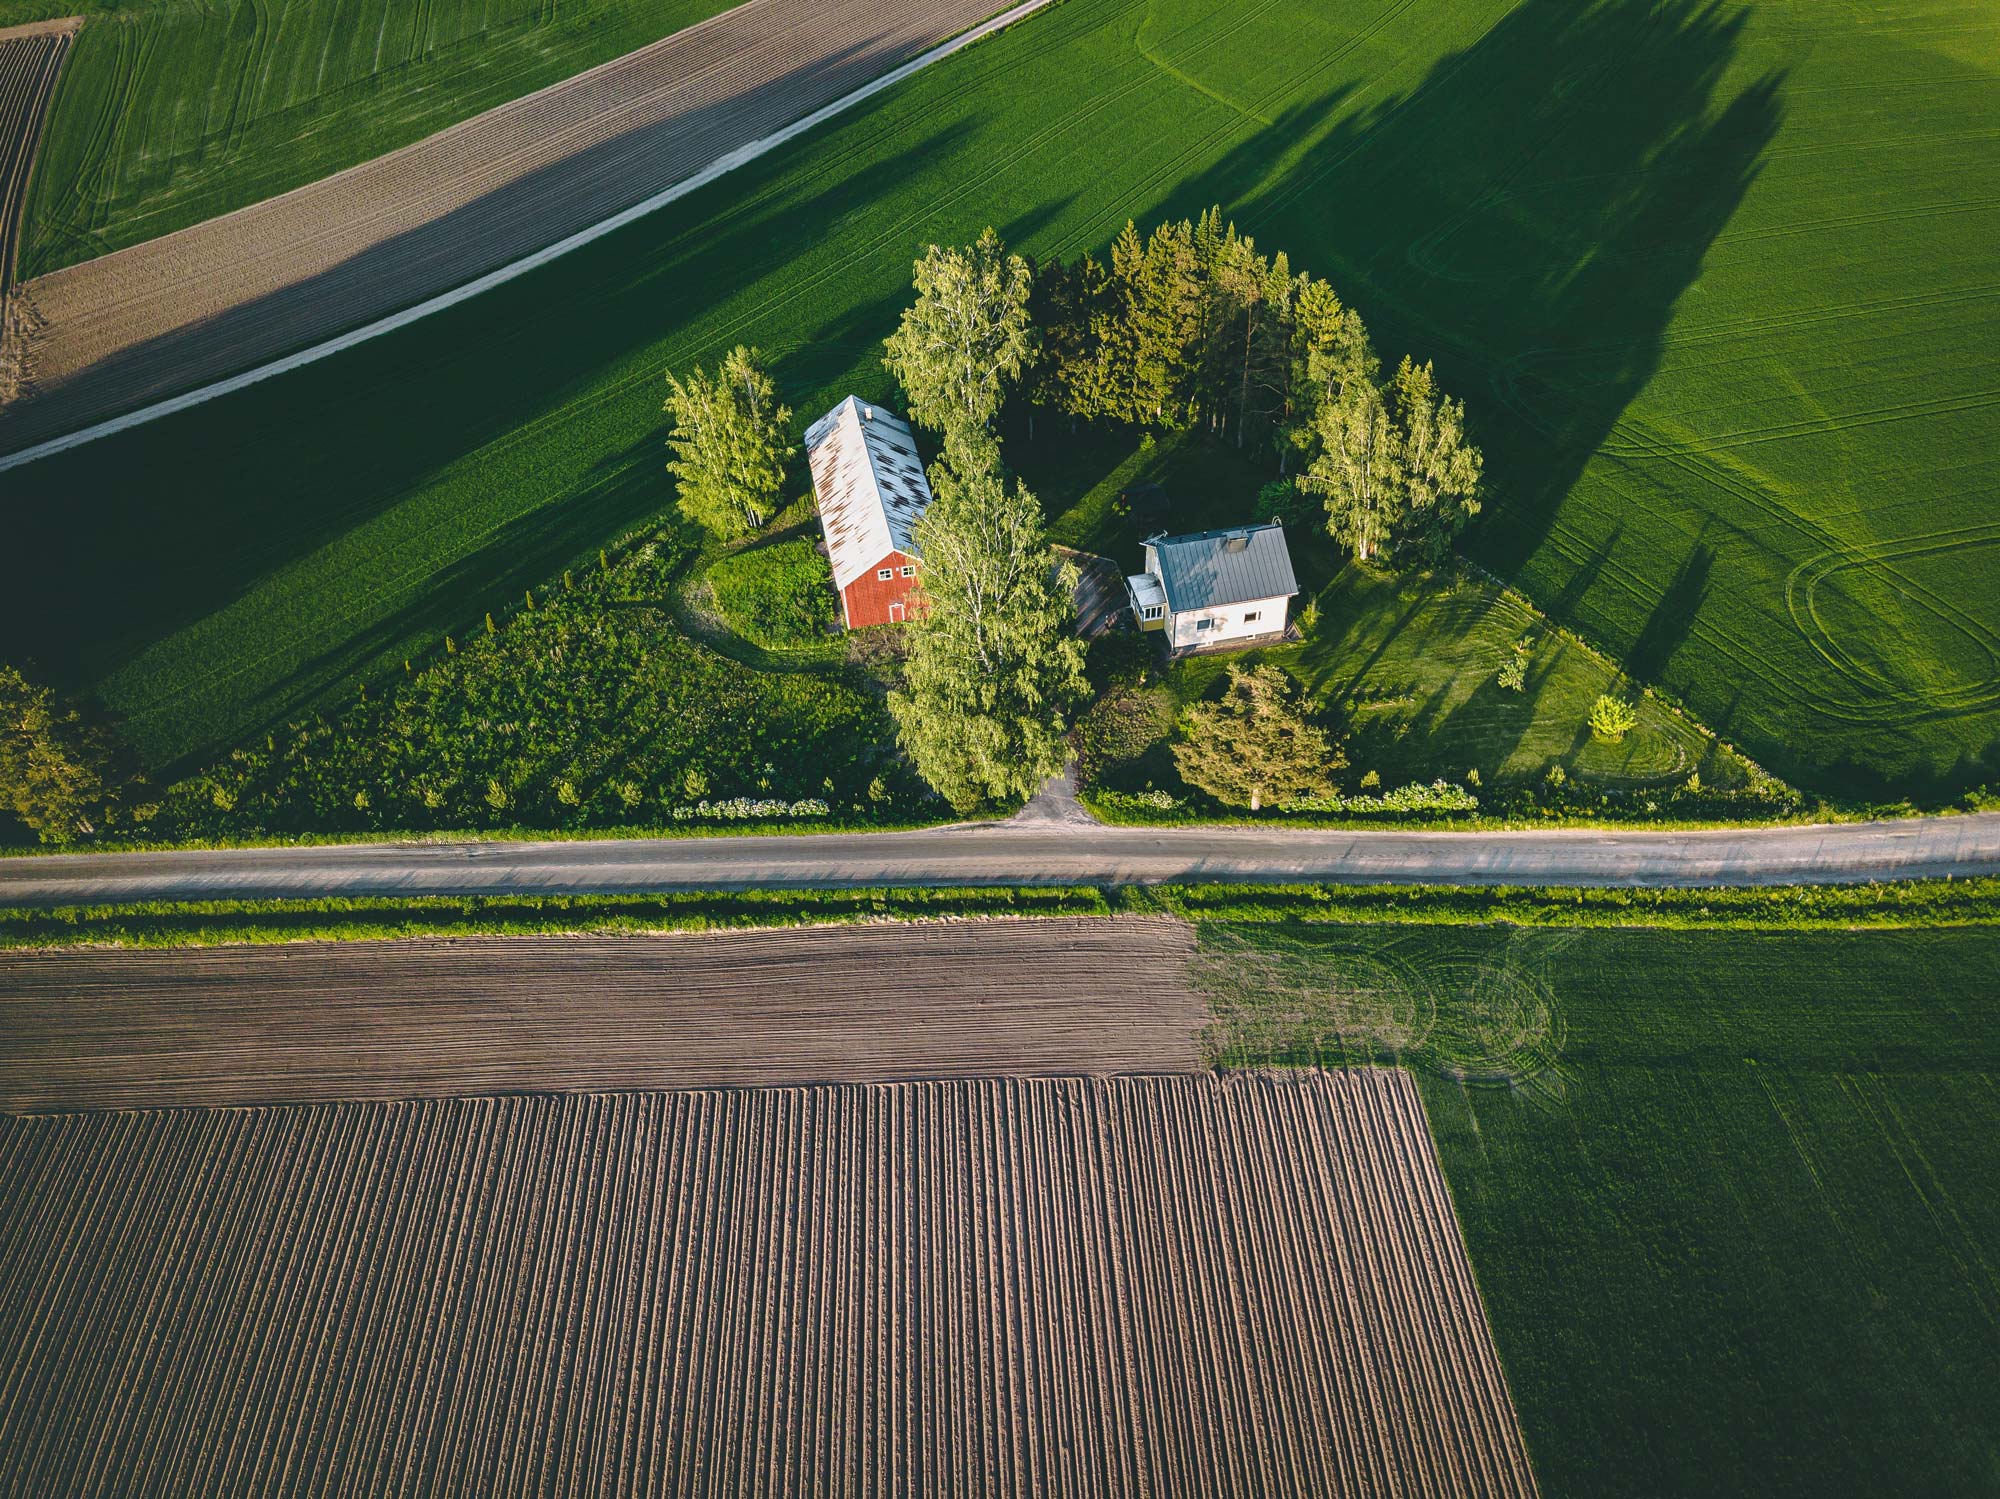
Buying, Building or Changing Your Rural Property?
Your insurance should keep up with your property.
It’s worth reviewing your coverage if you’re:
Buying a farm, acreage or rural property
Building or renovating a home, shop or outbuilding
Adding new equipment or vehicles
Starting or expanding a farming operation
Adding livestock or other agricultural activities
Converting a building to a new use
Renting out part of your property
Making significant improvements to your land or buildings
Even if nothing has changed, an insurance review can be a good way to make sure your coverage still reflects what you own and how you use it.
FAQ: Condo Insurance
Is farm insurance different from regular home insurance?
It can be. Farm and rural properties may have additional buildings, equipment, agricultural activities and liability exposures that aren’t typical of a standard residential property.
Do I need farm insurance if I just own an acreage?
Not necessarily. It depends on how the property is used. A rural residence or hobby acreage may have different insurance needs than an operating farm. It’s worth talking through your property and activities with a broker.
Can my outbuildings be covered?
Eligible structures such as garages, shops, barns and sheds may be covered, but the type, use and value of each building matter. Make sure your broker knows about all of the structures on your property.
What about my farm equipment?
Depending on the policy, eligible equipment and other property may be covered. It’s important to discuss what you own, where it’s stored and how it’s used when reviewing your coverage.
Does rural property insurance cover livestock?
Coverage for livestock and agricultural operations can depend on the policy and the nature of the operation. If you have livestock, tell your broker so they can help determine what coverage you need.
What if I operate a business from my rural property?
Running a business, farm operation or other commercial activity from your property can change your insurance needs. Be upfront about how the property is used so your coverage can be properly assessed.
Are wells and septic systems covered?
Coverage for wells, septic systems and related equipment can depend on the policy and circumstances. These are worth discussing when insuring a rural property.
Can you insure a rural property that isn't an active farm?
Yes. Rural properties can include acreages, hobby farms, seasonal properties and other rural residences. The right coverage depends on how you use the property and what’s located on it.