High-Value Home Insurance
Your home is worth more. Your insurance should account for it.
High-value homes come with higher stakes.
Custom finishes, premium materials, extensive renovations, valuable collections and high-end personal belongings can all add up quickly. A standard homeowners policy may not provide the limits or specialized coverage needed to properly protect everything you’ve built.
Garriock Insurance can help you find high-value home insurance designed around your property, your belongings and your lifestyle.
Your Home
Higher-value homes can have higher rebuilding costs, particularly when they include custom architecture, premium materials or specialized craftsmanship. Enhanced coverage can help account for the true cost of rebuilding your home following a covered loss.
Your Valuables
Jewellery, artwork, collectibles, wine, electronics and other high-value belongings may have limits under a standard homeowners policy. Specialized coverage can provide higher limits and more appropriate protection for valuable items.
Your Liability
Higher-value assets can also mean greater financial exposure. Enhanced personal liability coverage can provide additional protection if you’re held responsible for injury to someone or damage to their property.
Additional Living Expenses
If your home becomes uninhabitable following a covered loss, enhanced coverage may provide greater flexibility for temporary living arrangements while your home is repaired or rebuilt.
Coverage varies by policy and insurer. Your Garriock broker can explain what’s included and what specialized coverage may be available.
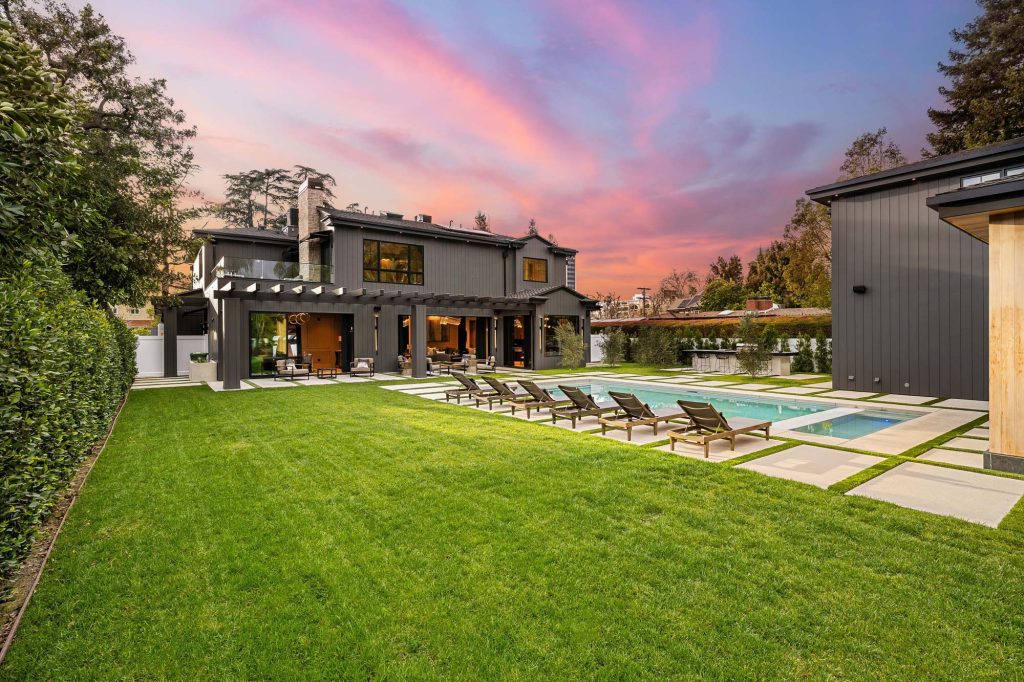
When "standard" isn't enough.
The value of a home isn’t always reflected in its market price.
Maybe you’ve built a custom home with premium finishes. Maybe you’ve completed extensive renovations. Maybe your home is filled with artwork, jewellery, collectibles or other high-value belongings.
Replacing those things can cost significantly more than a standard policy’s limits allow.
High-value home insurance can provide enhanced coverage and higher limits designed for properties and belongings that fall outside the typical homeowners insurance profile.
Not sure if your home qualifies as high-value? Just ask Garriock.
Your Home Isn't Off the Shelf. Your Insurance Shouldn't Be Either.
A custom home deserves more than an estimate based on square footage alone.
The materials, finishes, architecture, renovations and features that make your home unique can all affect what it would actually cost to rebuild.
The same goes for what’s inside it.
If you own valuable jewellery, artwork, antiques, collectibles, specialty equipment or other high-value belongings, we’ll help you identify where additional coverage may be appropriate.
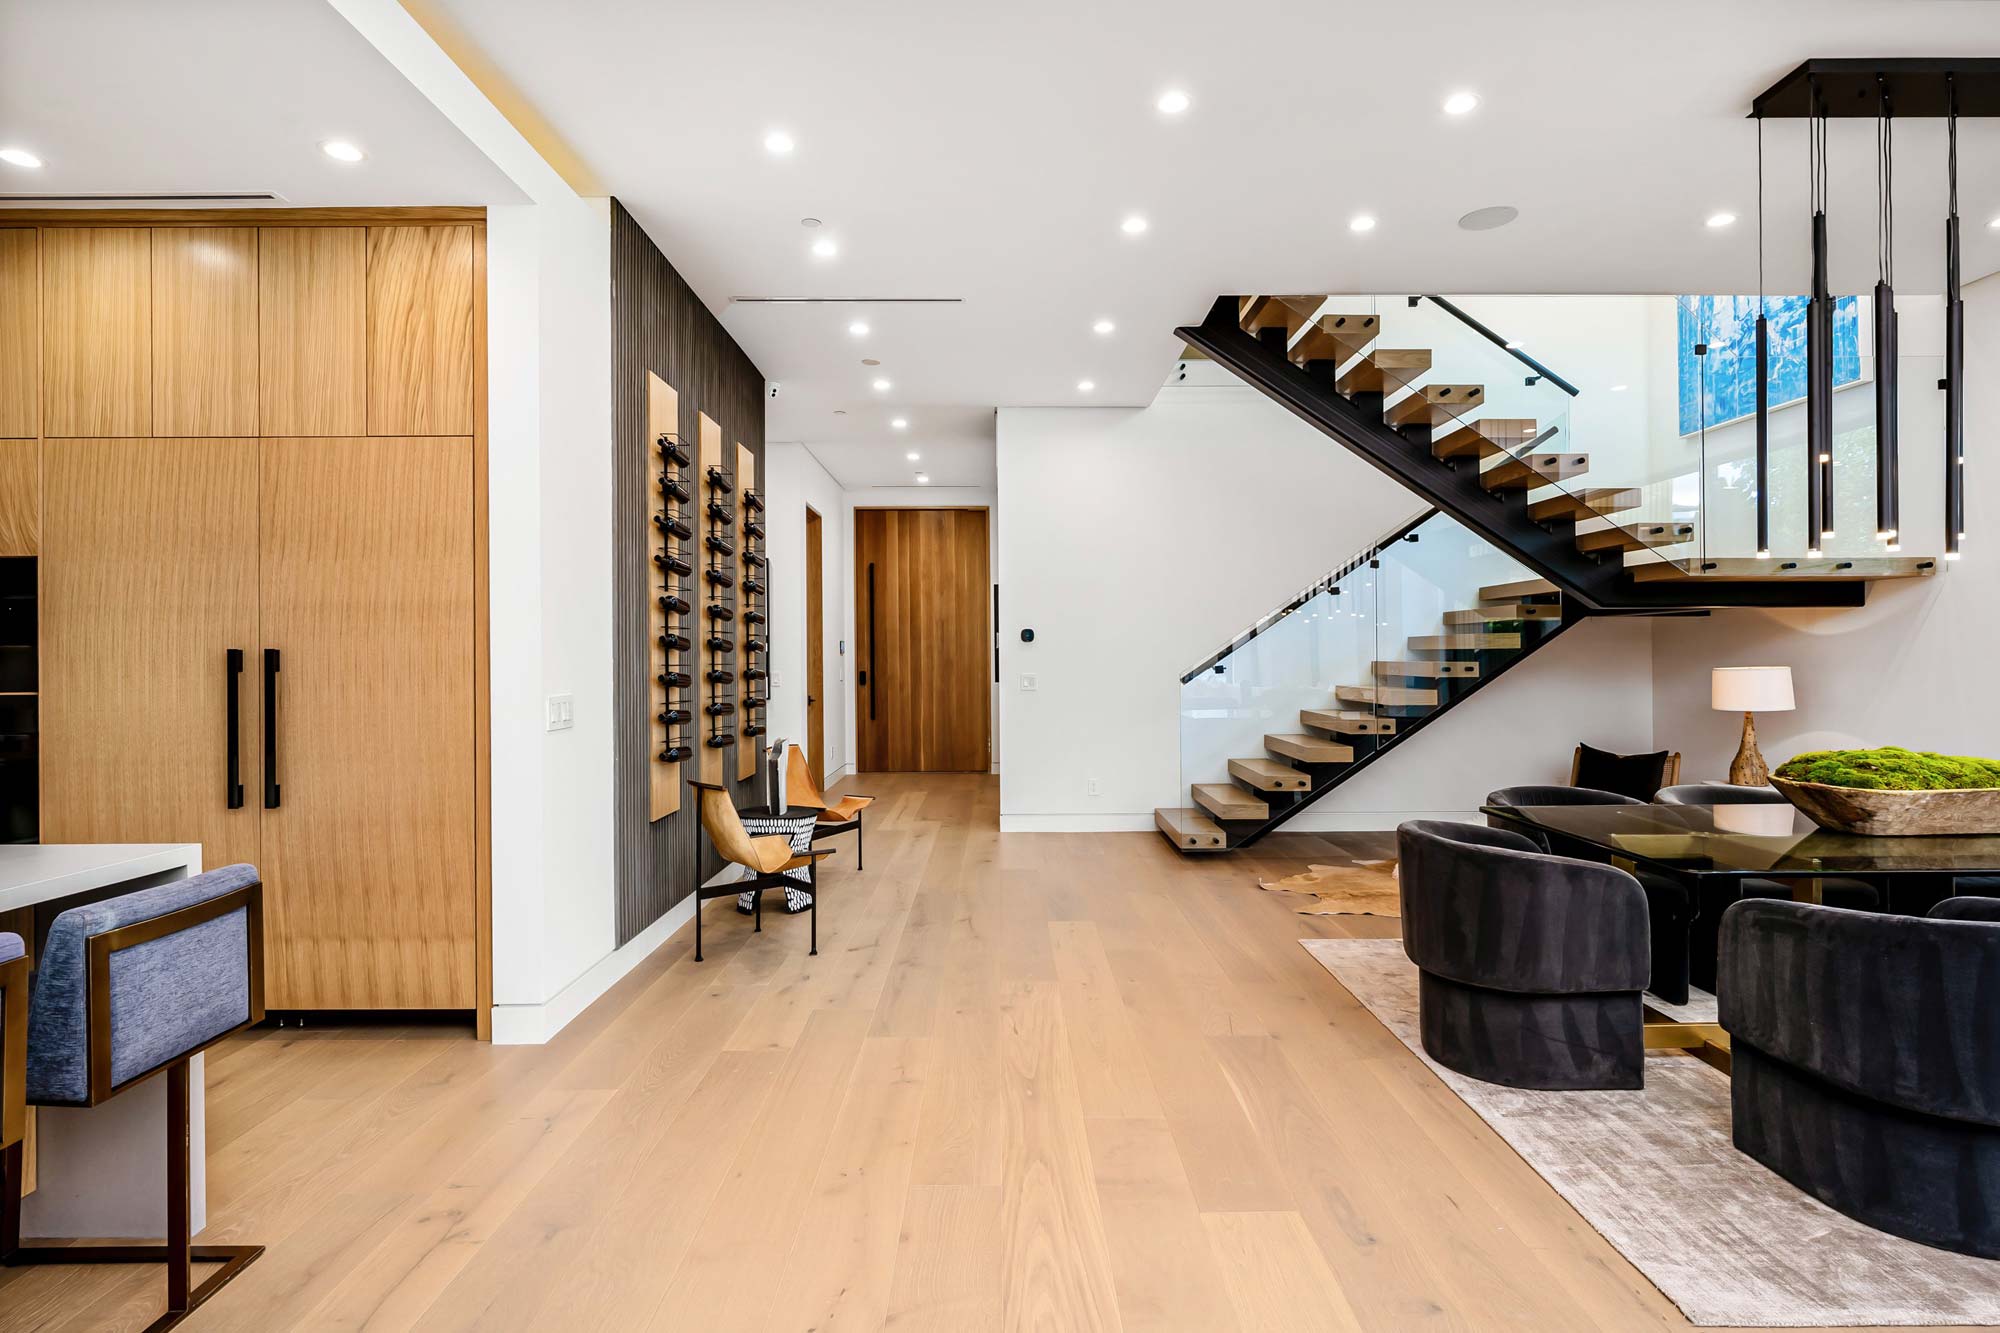
Have You Changed Your Home or Your Lifestyle?
Your insurance should keep up with your life.
A major renovation, custom addition, new collection or significant purchase can change what you need from your insurance.
It’s worth reviewing your coverage if you’ve:
Completed a major renovation or addition
Built a custom home
Purchased valuable jewellery or artwork
Started collecting high-value items
Added a pool, guest house or other significant feature
Made other major changes to your property
FAQ: High-Value Home Insurance
What is considered a high-value home?
There isn’t one universal definition. A home’s value, construction cost, features, location, finishes and the value of the belongings inside can all influence whether specialized high-value home insurance is appropriate.
If you’re unsure whether your home falls into this category, talk to a Garriock broker.
Is high-value home insurance different from regular homeowners insurance?
It can be. High-value policies may offer higher limits, broader coverage and specialized options designed for higher-value homes and belongings. The right solution depends on your property and circumstances.
Does high-value home insurance cover custom homes?
It can. Custom homes may have specialized materials, finishes, architectural features and construction requirements that can affect rebuilding costs. Your broker can help make sure your coverage reflects the home you’ve actually built.
Does it cover jewellery and artwork?
High-value home insurance can offer enhanced protection for valuable items such as jewellery, artwork, antiques and collectibles. Some items may require appraisals, scheduled coverage or other documentation.
Do I need to have my valuables appraised?
Some high-value items may benefit from or require an appraisal to establish their value and support appropriate coverage. Your broker can explain what documentation may be needed for specific items.
Does high-value home insurance provide more liability coverage?
Enhanced liability limits may be available with high-value home insurance. This can be particularly important for homeowners with significant assets to protect.
Does it cover my wine collection or other collectibles?
Specialized coverage may be available for certain collections, including wine, art, antiques and other valuables. The appropriate coverage depends on the type and value of the collection.
What happens if I renovate my home?
Major renovations can significantly change the cost to rebuild your home and the value of its contents. Let your broker know about substantial renovations or additions so your coverage can be reviewed and updated.
How do I know if my current home insurance is enough?
A good place to start is by reviewing your home’s estimated rebuilding cost, your policy limits and the value of your belongings. If you’ve made significant changes to your home or acquired valuable items, it’s worth having your coverage reviewed.